ServicesPrimary Auto Liability
Primary Auto Liability Insurance in Roswell, GA
Primary auto liability pays for injuries and damage your truck causes to other people, and your MC authority cannot run without it. We find a policy that fits your operation, get the proof filed with the FMCSA and explain every line before you sign.
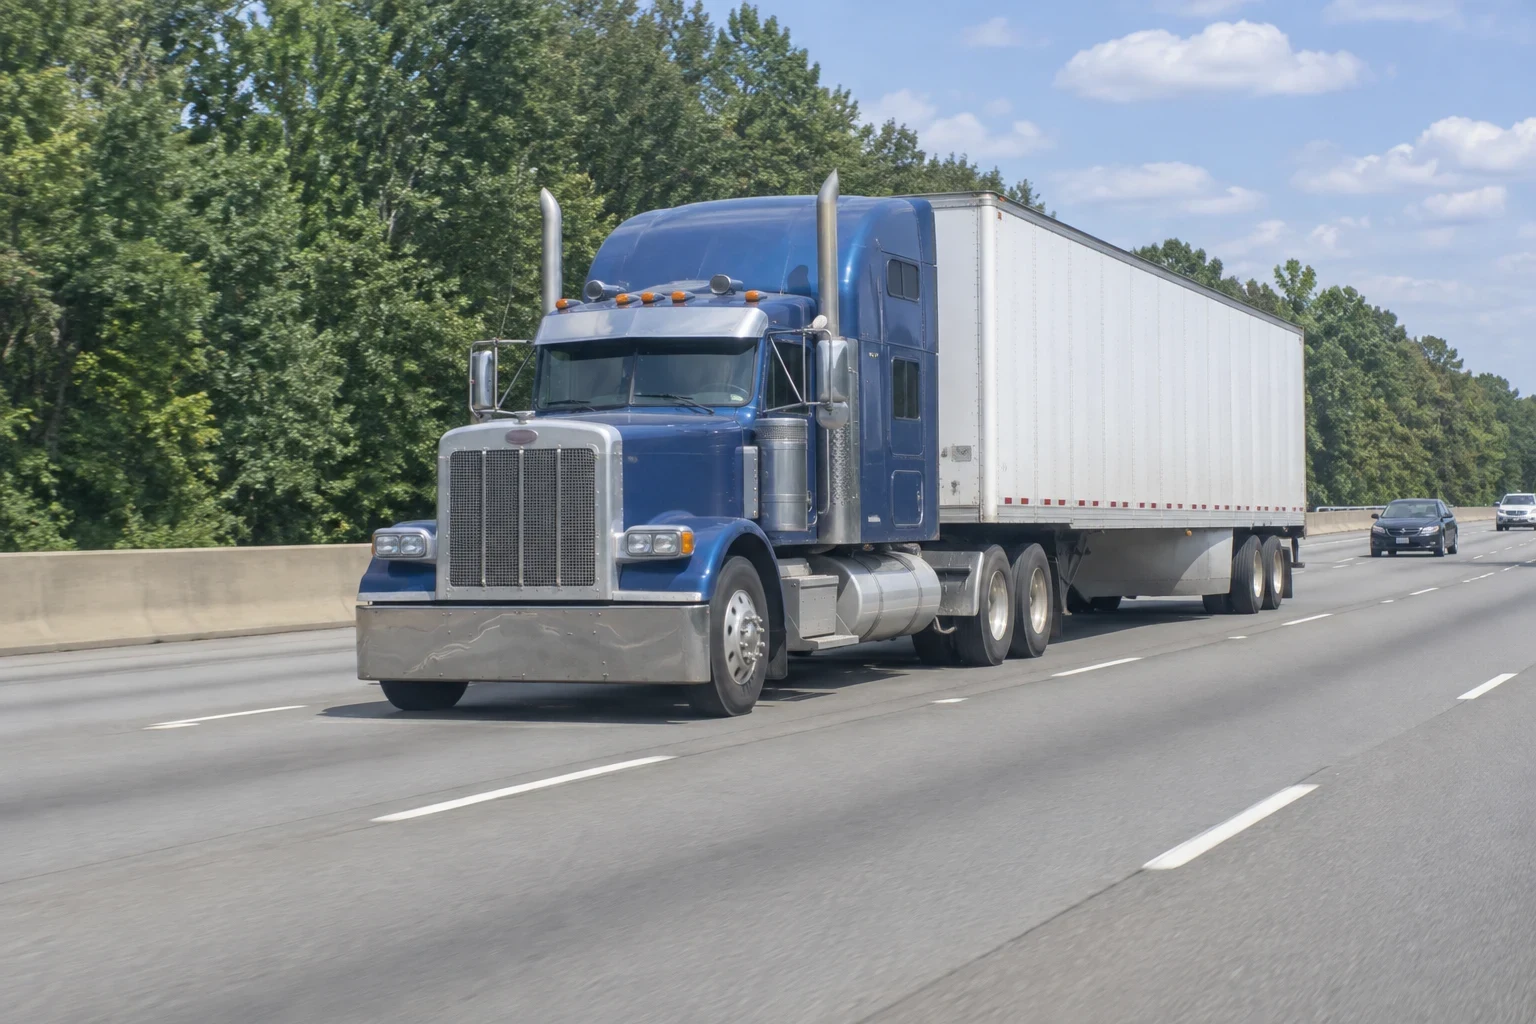
The coverage your authority rests on
Primary auto liability covers bodily injury and property damage to others when your truck is at fault. If you rear-end a car in traffic or clip a loading dock, this is the policy that answers. It does not repair your own truck or pay for the freight on your trailer. Those are physical damage insurance and motor truck cargo insurance, and we can quote them alongside.
For-hire interstate carriers have to keep liability on file with the FMCSA to keep MC authority active. Brokers and shippers will ask for a certificate of insurance before they load you, and many set limits above the federal minimum. Getting the limit right and the filing in on time matters as much as the premium.
We have been in business 5 years and are licensed for property and casualty insurance. We treat each file the way we would for a neighbor down the street: plain answers, and no pushing coverage you do not need.
What we handle on your liability policy
- Limits matched to your contracts
- We look at what your brokers and shippers actually require, not just the legal floor. Then we quote limits that let you take the loads you want.
- Federal and state filings
- We make sure the BMC-91 or BMC-91X reaches the FMCSA so your authority shows active coverage. If you also run intrastate in Georgia, we handle the state filing too.
- The MCS-90 endorsement
- Interstate for-hire policies carry the MCS-90, which protects the public after a crash. We explain what it means for you, including that the insurer can seek repayment from you if a loss would otherwise have been excluded.
- Certificates of insurance
- Tell us which brokers and shippers need proof, and we issue certificates with them listed as holder.
- Listed trucks and drivers
- We schedule your trucks by VIN and your drivers by name, so nobody is guessing at claim time about who and what is covered.
- A real renewal review
- Before each renewal we go back over your loss runs, drivers and lanes so the policy keeps up with how you run today.
Signs it is time to set up or review your liability
Your authority is pending
New MC authority will not go active until the FMCSA sees a liability filing. Our New Authority Truck Insurance page covers the rest of a first-year setup.
You are leaving a lease
While leased on, the carrier's policy covered you under dispatch. Running under your own authority means you need your own primary policy, and bobtail coverage will not fill that gap.
A broker wants a higher limit
If good loads keep going to someone else because your limit falls short, it is worth pricing an increase.
You added a truck or driver
Unlisted units and drivers cause trouble after an accident. Let us know before the new driver's first load.
Your renewal jumped
A sharp increase can come from a claim, a violation on one driver's record or a shift in the market. We find out which and shop it.
A cancellation notice arrived
A lapse in liability can lead to an FMCSA revocation notice. Reach out as soon as it lands so we can work on getting coverage and the filing back in place.
How getting your liability quote works
- 1
A conversation first
We start with your DOT number, your MC authority, what you haul and how far you run. You can talk with us by phone, by video or at our office in Roswell.
- 2
Gathering the details
We ask for driver names, dates of birth and CDL numbers, truck VINs and loss runs from any past insurer. A new venture with no loss history is fine; we tell the insurance companies that up front.
- 3
Shopping and comparing
We take your file to the insurance companies we work with and compare what comes back on limits, exclusions and premium, not just the bottom number.
- 4
Walking through the quote
We go line by line with you, including the down payment and payment schedule, so nothing surprises you after the policy starts.
- 5
Binding and filing
Once you approve, we bind the policy, get the federal filing submitted and send certificates to the brokers and shippers on your list.
What moves the price of primary liability
Primary auto liability is often the biggest single premium a trucking business pays. Insurers price the risk your trucks put on the road, so the number depends on how you run and who is driving. We will tell you which factors are driving your quote and which ones you can change.
- Radius and lanes
- Local and regional work usually prices differently than long haul across many states. Heavy urban traffic adds exposure.
- What you haul
- General freight, dirt and gravel, vehicles and hazmat each carry a different risk profile, and the premium follows.
- Your drivers
- Years with a CDL, age, violations and accidents on each driving record weigh heavily. One driver with a rough record can lift the price for the whole policy.
- Time in business and claims
- New authorities pay more in the early years. A clean loss record built over time is one of the strongest tools for bringing premium down.
- Limits and number of units
- Higher limits cost more, and each added power unit adds premium. Where the trucks are garaged also plays a part.
Questions about primary auto liability
Something not covered here? (770) 285-5789
Does primary liability pay to fix my truck if I wreck it?
No. It pays for injury and damage to other people and their property. Repairing or replacing your own truck takes physical damage insurance, which we can quote at the same time.
What is the difference between primary liability and bobtail?
Primary liability covers you while you operate under your own authority or under dispatch. Non-trucking liability, often called bobtail, covers a leased owner-operator driving off dispatch, while the motor carrier's primary policy handles dispatched work. If you run your own authority, you need primary.
How soon does my filing show up with the FMCSA?
After the policy is bound, the insurer submits the filing electronically. It often posts within days, but FMCSA processing is outside our control. We check your record and let you know once it shows.
Can I get liability with brand new authority?
Yes. Several insurance companies write new ventures, though premiums and down payments tend to run higher in the first year. Clean driving records and prior CDL experience help a lot.
Do I really need more than the federal minimum?
The law sets a floor, but many brokers and shippers want a higher limit before they will tender loads. We look at the work you want and recommend a limit that fits it. Then we show you the price difference so the choice is yours.
Let's get your liability set up right
Have your DOT number and a list of your trucks and drivers handy, and we will take it from there. You will get plain answers about limits, filings and premium.