ServicesHotshot Truck Insurance
Hotshot Truck Insurance in Roswell
Your pickup and gooseneck are how you earn a living, and your policy should cover them that way. We set up hotshot coverage that matches your truck, your trailer and the freight you haul, then explain every line before you sign.
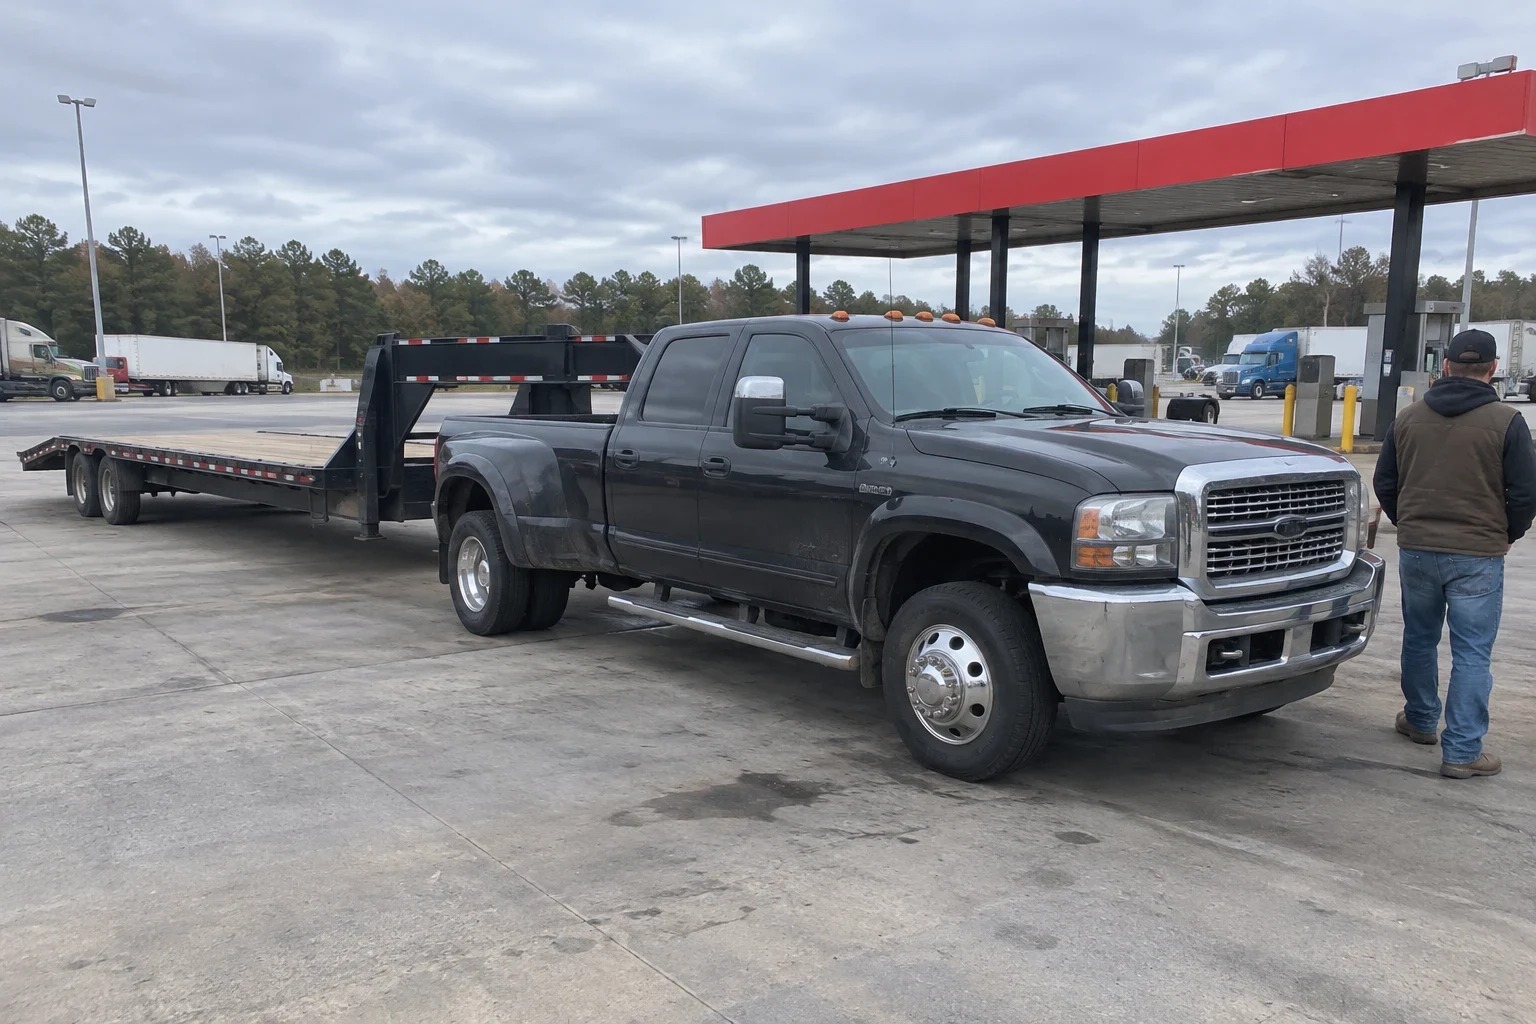
Coverage for one truck, one trailer and a lot of miles
Hotshot work sits in an odd spot. You run a one-ton or medium-duty pickup, often a dually, pulling a flatbed or gooseneck trailer, and you haul time-sensitive loads for brokers and shippers. Once that combination runs for hire, a personal auto policy stops being the right fit, and many carriers will not touch it at all.
A proper hotshot policy usually pairs primary auto liability with motor truck cargo coverage, and adds physical damage for the truck and trailer if you want them protected. If you run under your own MC authority, the liability carrier also files proof of coverage with the regulators so your authority stays active.
We have been in business 5 years, helping owner-operators around Roswell and the north Fulton area get this sorted. We treat it the way we would for a neighbor down the street: plain answers, no pressure, and a policy you understand.
What a hotshot policy can include
Primary auto liability
Covers injuries and property damage you cause to others while hauling. It is the coverage brokers and regulators look at first, and the limit has to meet what your authority and your contracts require.
Motor truck cargo
Protects the freight on your deck, from steel and pipe to equipment and building materials. We check the cargo limit against what your brokers ask for and flag any commodity exclusions before they surprise you.
Physical damage for truck and trailer
Comprehensive and collision for the pickup and the trailer, each listed with its own value. If either is financed, your lender will likely require it.
Filings and certificates
When you run under your own authority, your liability carrier handles the required filings. We also send a certificate of insurance to the brokers and shippers you work with, naming them where they ask.
Optional add-ons
Non-trucking liability if you lease on to a carrier, plus towing, downtime or trailer interchange coverage where your work calls for it. We only suggest these when they fit how you actually run.
Signs it is time to look at hotshot coverage
Your pickup is on a personal policy
If you are hauling for pay on a personal auto policy, a claim could be denied outright. That is the most common gap we see with new hotshot drivers.
You just got your DOT number or MC authority
A new authority needs active liability coverage and a filing on record before you can legally run loads.
A broker asked for higher cargo limits
Some loads require more cargo coverage than your current policy carries. Losing a load over a limit is avoidable.
You bought a new trailer or second truck
Equipment has to be listed on the policy by VIN. A trailer that is not scheduled may not be covered for physical damage.
Your renewal jumped and nobody explained why
A rate change usually has a reason, like a claim, a new driver or a lane change. We will walk through it with you and shop it if that makes sense.
How we set up your hotshot policy
- 1
A conversation first
You call, and we talk through your operation: what you haul, how far you run, who drives, and if you run under your own authority or are leased on to a carrier. You can meet us at our office or talk by phone or video.
- 2
Gathering the details
We collect your DOT number, VINs for the truck and trailer, driver license information and any loss history. Having these ready keeps things moving.
- 3
Comparing options
We are licensed for property and casualty insurance and shop the carriers that write hotshot risks. You get the options side by side, with limits, deductibles and exclusions spelled out.
- 4
Binding and paperwork
Once you pick a policy, we bind coverage, confirm the filings are submitted and send certificates to your brokers. After that, we are a phone call away when you add equipment or need another certificate.
What shapes your hotshot premium
Hotshot pricing depends heavily on the driver and the operation, so two trucks of the same model can price very differently. We will tell you which factors are driving your number and which ones you can change. No quote is final until a carrier reviews your details.
- Driving record and experience
- Years of commercial driving and a clean record carry a lot of weight. Newer drivers often see higher rates for the first couple of years.
- Age of your authority
- New authorities usually cost more until there is a track record. Rates often improve at renewal as that history builds.
- Freight and radius
- Heavy equipment, steel or high-value loads raise cargo exposure. Long interstate runs generally price higher than regional work.
- Equipment values and deductibles
- A newer dually and trailer cost more to cover for physical damage. A higher deductible can lower the premium if you can handle it after a claim.
Hotshot insurance questions
Something not covered here? (770) 285-5789
Can I keep my pickup on my personal auto policy?
Not if you are hauling freight for hire. Personal policies typically exclude commercial use, which means a claim could be denied. A commercial policy is written for exactly this kind of work.
Do I need cargo coverage if the broker does not ask for it?
Most brokers and shippers do ask, and the ones that do not still expect you to cover damage to their freight. Without cargo coverage, a damaged load can come out of your own pocket. We usually recommend carrying it.
Can I get coverage with a brand-new MC authority?
Yes. Fewer carriers write new hotshot authorities, and pricing tends to be higher in the first year, but coverage is available. We help you get it bound so the filing can go on record and you can start hauling. Our New Authority Truck Insurance page covers this in more depth.
I only run loads inside Georgia. Does that change anything?
It can. Intrastate work may have different filing requirements than interstate work, and a shorter radius can affect pricing. Tell us where you run and we will set the policy up to match.
How do I get a certificate of insurance to a broker?
Give us a call with the broker's name and any specific wording they need. We send the certificate to them directly, so you are not waiting on paperwork to book a load.
Let's get your hotshot rig covered properly
Tell us about your truck, your trailer and the loads you run. We will explain your options in plain terms and help you pick the one that fits.