ServicesOwner-Operator Insurance
Owner-Operator Truck Insurance in Roswell
When the truck is yours, every gap in coverage comes out of your pocket. We talk it through with you by phone, video or at our office, sort out what your lease or authority already covers, and add only the coverage that is actually missing.
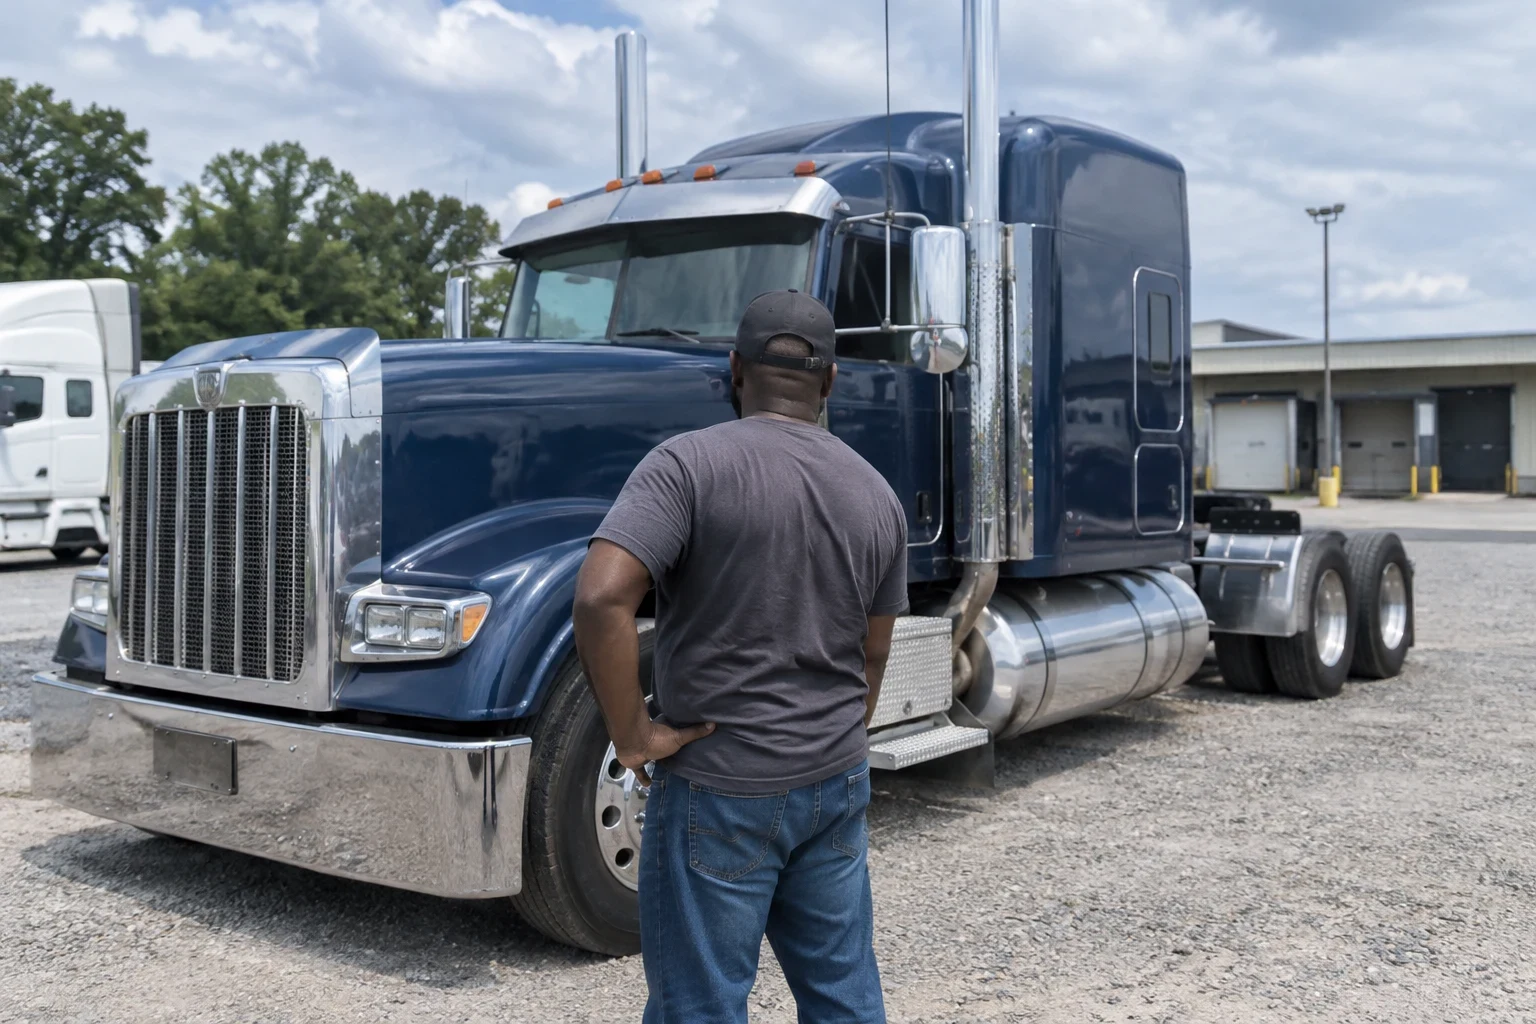
Insurance Built Around How You Actually Run
Owner-operators fall into two camps, and the right coverage depends on which one you are in. If you are leased onto a motor carrier, the carrier usually carries primary liability while you are under dispatch, and your job is to cover the truck itself and the time you drive it off dispatch. If you run under your own MC authority, you carry it all: primary liability, cargo coverage, physical damage and the federal filings that keep your DOT number active.
We have been in business 5 years, and a lot of that time has gone into helping drivers in Roswell and nearby towns like Alpharetta, Marietta and Woodstock sort out exactly this. We are licensed for property and casualty insurance, and we explain each line of a policy in plain words before you sign anything.
Treat us like the neighbor down the street who happens to know insurance. You ask the questions, we give you straight answers, and nobody pushes coverage you do not need.
What an Owner-Operator Policy Can Include
Primary auto liability
Required when you run your own authority. It pays for injuries and damage you cause to others, and it is the coverage the FMCSA filing is built on. Our Primary Auto Liability Insurance page goes deeper.
Non-trucking liability
For leased-on drivers, this covers you when you are driving the truck off dispatch, like heading home or to the shop. Many carriers require it before they will sign your lease.
Physical damage
Covers your tractor, and your trailer if you own one, against collision, theft, fire and weather. If you are still paying off the truck, your lender will almost certainly require it.
Motor truck cargo
Protects the freight you haul. Brokers and shippers often set the minimum limit, so we check those requirements before we quote.
Trailer interchange
Needed when you pull trailers you do not own under an interchange agreement. We read the agreement with you so the limit matches what it asks for.
Filings and certificates
We handle the federal filings for your authority and send certificates of insurance to brokers and carriers when you need them.
Signs Your Coverage Needs a Second Look
You are moving from leased-on to your own authority
Your carrier's liability stops covering you the day you go independent. You will need primary liability and filings in place before you can haul your first load.
A broker rejected your certificate
This usually means a cargo limit is too low or a coverage line is missing. We can usually tell you what was flagged after one look at the certificate.
You bought or financed a new truck
A higher-value truck changes your physical damage limit, and lenders often want themselves listed as loss payee.
You are not sure what covers you off dispatch
If you cannot say what happens when you drive home on a Friday evening, you may be missing non-trucking liability. That gap is common and worth fixing.
Your renewal jumped and nobody explained why
We will walk through your loss runs and rating details so you know what changed and whether shopping it makes sense.
How Getting Covered Works With Us
- 1
A first conversation
We talk by phone, video or in person at our office. You tell us how you run, what you haul, how far you go, and if you are leased on or running under your own authority.
- 2
Gathering the details
We ask for your CDL, driving record details, truck VIN and value, DOT number, and any lease or broker requirements. If you have prior coverage, loss runs help a lot.
- 3
Quotes laid out side by side
We show you what each quote covers, what the deductibles are and where one policy is thinner than another. You pick what fits your operation and budget.
- 4
Binding, filings and certificates
Once you decide, we bind coverage, take care of any required filings and get certificates to whoever needs them. Then we stay reachable when your lease, truck or lanes change.
What Shapes Your Premium
Insurers price an owner-operator policy on risk, and most of that risk comes from a handful of details about you and your truck. We go through each one with you so the number on the quote makes sense. Some factors you can change over time, and we will point those out.
- Driving record and experience
- Years with a CDL and a clean record carry a lot of weight. Recent violations or accidents push premiums up for several years.
- Authority status
- Leased-on drivers usually pay less because the carrier holds primary liability. New authorities often see higher rates until they build a history.
- Radius and freight
- Long-haul routes and higher-risk commodities cost more to insure than short local runs with general freight.
- Truck value and deductibles
- A newer, more valuable truck raises physical damage costs. Choosing a higher deductible lowers the premium but means more out of pocket after a claim.
- Garaging location and loss history
- Where the truck is parked and any prior claims both factor in. Clean loss runs from past policies help.
Owner-Operator Insurance Questions
Something not covered here? (770) 285-5789
I am leased onto a carrier. What do I actually need to buy?
Usually non-trucking liability and physical damage on your own truck. The carrier typically holds primary liability and often cargo while you are under dispatch. Your lease spells this out, and we are glad to read it with you so you are not paying twice for the same coverage.
What changes when I get my own MC authority?
You become responsible for primary liability, cargo coverage and the federal filings tied to your authority. Your coverage must be in place and filed before your authority goes active. Our New Authority Truck Insurance page covers that first year in more detail.
Can you send certificates to my brokers?
Yes. Tell us who needs one and we will send the certificate of insurance. If a broker needs to be added as certificate holder or wants a specific limit, we will check your policy and let you know what that takes.
Do I have to come to your office?
No. Many drivers handle everything by phone or video from the road. If you are around Roswell and would rather sit down face to face, our office works too.
My premium seems high. Can you help?
We can look at your current policy, your deductibles and your loss history to see where the cost comes from. Sometimes adjusting a deductible or correcting a radius helps, and sometimes another insurer rates you differently. We will tell you honestly which is the case.
Let's Get Your Truck Covered Right
Bring your lease, your DOT number or just your questions. We will explain what you have, what you need and what it is likely to cost, with no pressure either way.