ServicesBox Truck Insurance
Box Truck Insurance in Roswell
Running a box truck for last-mile delivery, furniture moves or contract freight? We put together liability, cargo and physical damage coverage that matches the work you actually do, then explain every line before you sign anything.
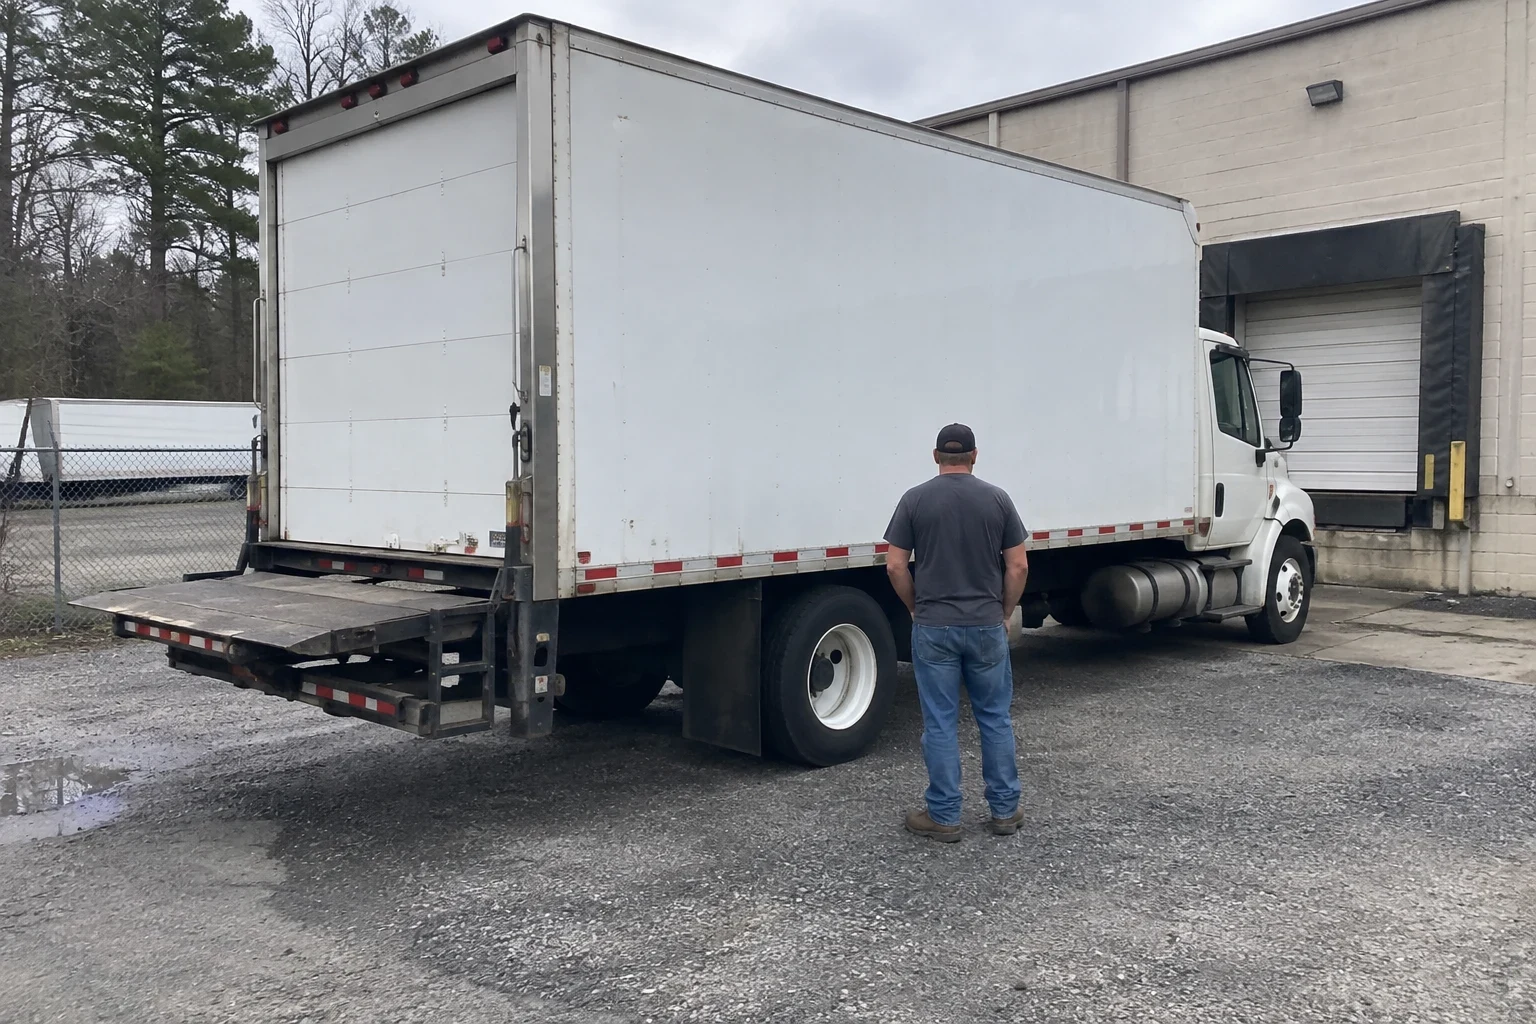
Coverage built around how your box truck earns
Box trucks sit in an odd spot. Many run without a CDL, yet the moment you haul for hire you are a motor carrier with the same expectations as a tractor-trailer outfit: liability limits, cargo coverage, a certificate of insurance before the first load, and often a DOT number and MC authority.
A personal auto policy will not cover any of this, and a generic commercial auto policy may leave gaps around the freight in the back or the liftgate on the rear. We have been in business 5 years and are licensed for property and casualty insurance, so we can place the pieces together and walk you through how they fit.
We treat each call like a neighbor asking for help. You tell us what you haul, where and for whom. We tell you what you need, what is optional and why.
What a box truck policy usually includes
Primary auto liability
Pays for injuries and damage you cause to others on the road. It is the coverage brokers, shippers and regulators check first, and the one your filings rest on.
Motor truck cargo
Protects the freight in your box, from parcels to furniture moves to palletized retail stock. We check the exclusions with you, since some policies limit electronics, unattended trucks or certain commodities.
Physical damage
Covers your own truck for collision, theft, fire and weather. If the truck is financed or leased, your lender will likely require it.
Filings and certificates
We handle the insurance filings tied to your authority and send certificates of insurance to the brokers and customers who ask for them.
Optional add-ons
Depending on your operation, that can include general liability for loading docks and customer sites, reefer breakdown for refrigerated boxes, or non-trucking liability if you are leased to another carrier. See Non-Trucking Liability (Bobtail) Insurance for that last one.
Signs your box truck coverage needs a closer look
- You started hauling for hire
- If you moved from carrying your own goods to hauling for paying customers, your old policy may not cover the new work. That change usually means filings and higher limits too.
- A broker asked for higher limits
- Load boards and delivery contracts often set minimum liability and cargo limits. If you are turning down work because your certificate falls short, it is time to talk.
- You added a truck or a driver
- Each new unit and each new driver changes your policy. Adding them late can leave a gap right when you need the coverage.
- Your cargo changed
- Going from parcels to appliances or refrigerated food changes your cargo risk. Your cargo coverage should change with it.
- Renewal came in higher and nobody explained why
- We will look at the policy with you and point out what is driving the premium, and what you can actually do about it.
How getting covered works with us
- 1
A conversation about your operation
By phone, video or at our office, we ask about your truck, its weight rating, your routes, your drivers and what you haul. Have your DOT number and MC authority handy if you have them.
- 2
Shopping the right markets
We take your details to carriers that write box truck risks and compare what comes back. Not every insurer wants last-mile delivery or moving work, so knowing where to look saves time.
- 3
Going over the options plainly
We lay out each option side by side: limits, deductibles, exclusions and premium. You pick what fits your budget and your contracts.
- 4
Binding, filings and certificates
Once you decide, we bind coverage, take care of any required filings with the agencies and send certificates of insurance to the brokers or customers waiting on them. After that, one phone call to us handles changes, renewals and questions.
What moves the price of box truck insurance
No two box truck premiums look alike, even for the same model of truck. The price comes from your operation, your drivers and what you carry. We will show you which of these matter most in your quote.
- Driver history
- Violations, accidents and years of commercial driving experience weigh heavily. A clean record for every driver on the policy makes a real difference.
- Type of work and cargo
- Furniture moving, parcel delivery, refrigerated food and general freight all carry different risks. Higher-value or more fragile loads raise cargo costs.
- Radius and routes
- Local runs around the north metro price differently than long regional trips. How far you go and how often both count.
- Limits and deductibles
- Higher liability and cargo limits cost more, and higher deductibles can lower the premium. We help you match limits to what your contracts actually require.
- Time in business
- Newer authorities usually pay more until they build a track record. If that is you, our New Authority Truck Insurance page explains what to expect.
Box truck insurance questions we hear often
- Do I need commercial insurance if my box truck does not require a CDL?
- Yes, if you use it for business. The CDL question is about the driver's license, not insurance. Any truck hauling goods for pay needs commercial coverage, and personal policies typically exclude that use.
- Do I need a DOT number and MC authority for a box truck?
- It depends on the truck's weight rating and whether you cross state lines or haul for hire. Many box truck operators need a DOT number, and those hauling regulated freight for others across state lines usually need MC authority as well. We can talk through your situation and explain what filings your coverage needs to support.
- I deliver under contract for a larger company. Does their insurance cover me?
- Sometimes partly, often not. Some contracts require you to carry your own liability, cargo and physical damage. We can read the insurance section of your agreement with you and point out what you are responsible for.
- Will my cargo coverage pay if something is stolen from the truck overnight?
- Not always. Many cargo policies have unattended vehicle conditions, such as requiring the truck to be locked or parked in a secured lot. We show you those conditions in writing before you buy so there are no surprises at claim time.
- How fast can I get a certificate of insurance for a broker?
- Once coverage is bound, we send certificates to brokers and shippers as they request them. Before that, we can tell you what information the broker needs so your paperwork matches their requirements.
Ready to get your box truck properly covered?
Give us a call and tell us about your truck and the work you do. We will explain your options in plain language and help you choose coverage that fits.