Can I Get Just Cargo Insurance for My Truck in Roswell?
A standalone cargo policy is a real option for some drivers, and the deciding factor is usually whose authority you run under.
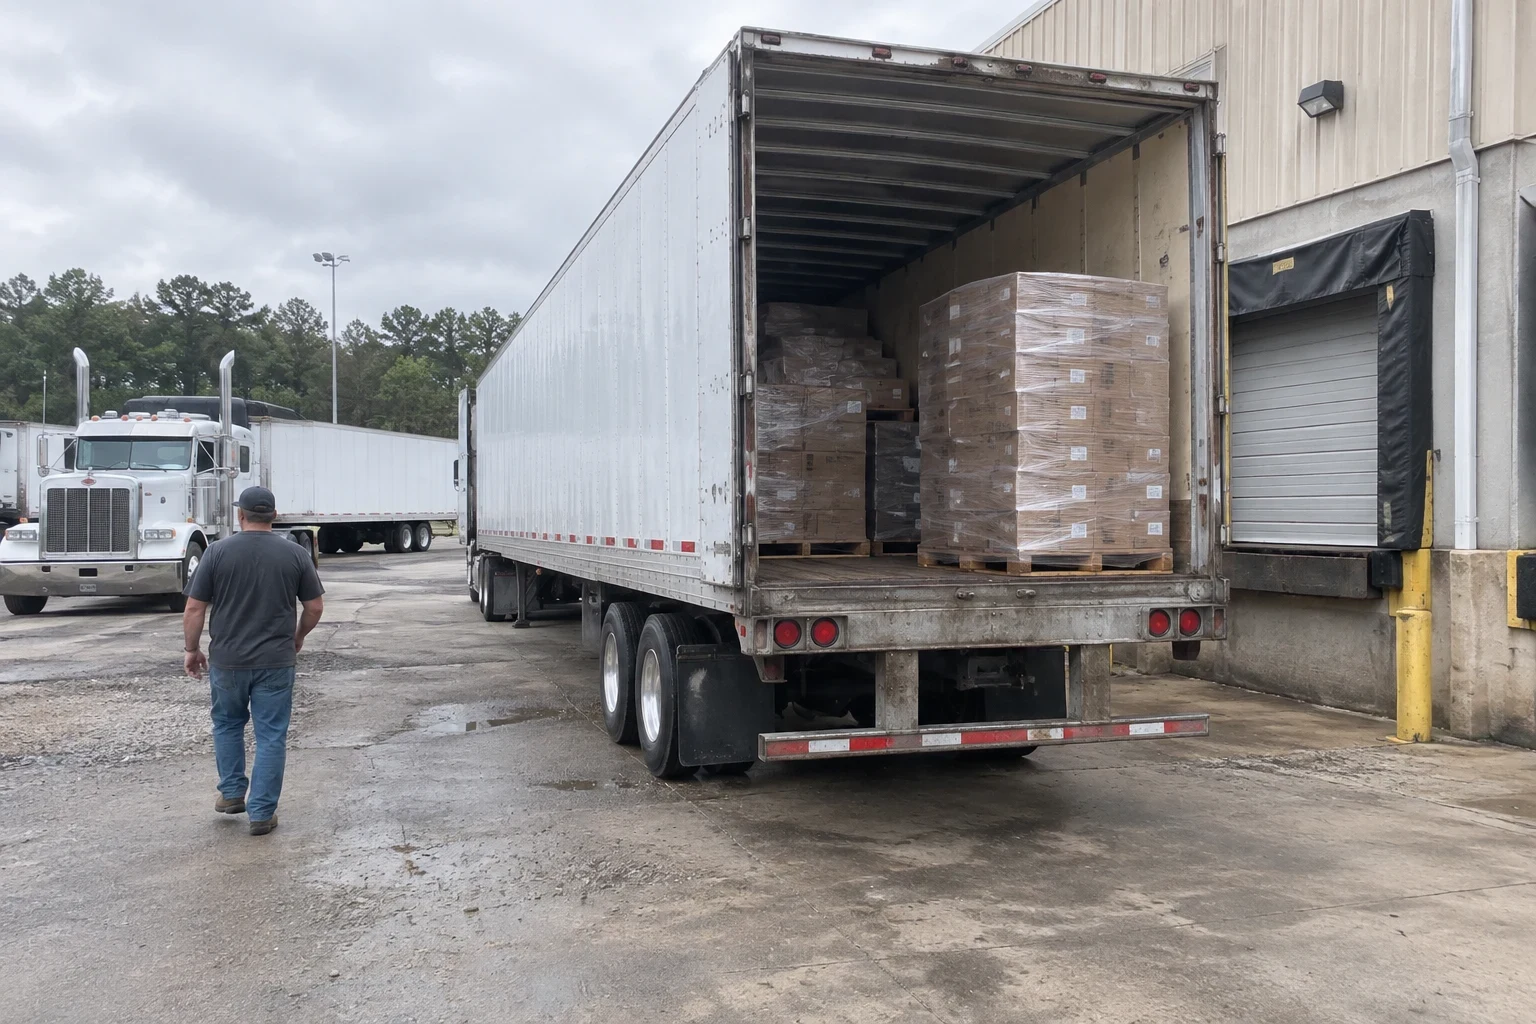
Can I get just cargo insurance?
Yes, you can often buy motor truck cargo insurance on its own, usually when you are leased to a motor carrier that already covers liability. If you run under your own MC authority, cargo alone will not keep your authority active, because federal filings require primary auto liability. We can sort out which case fits you at (770) 285-5789.
When does a cargo-only policy make sense?
The most common fit is an owner-operator leased onto a motor carrier. The carrier's policy usually handles primary auto liability while you are under dispatch, and your lease agreement may ask you to carry your own cargo coverage. In that setup, a separate cargo policy fills the gap the lease leaves open.
Some drivers also add cargo on its own when the carrier they lease to carries cargo coverage with a high deductible that gets charged back to the driver. Your own policy can soften that hit. We read the lease with you so you know exactly what the carrier covers and what lands on you.
- Leased owner-operators whose lease requires their own cargo coverage
- Drivers who want protection from deductible chargebacks on the carrier's cargo policy
- Operators adding cargo midyear because a new broker or shipper asked for it
Why cargo alone won't work under your own MC authority
Once you have your own DOT number and MC authority for for-hire freight, the FMCSA requires proof of primary auto liability before your authority goes active. Your insurer files that proof electronically. Cargo coverage does not satisfy that filing, so a cargo-only policy leaves your authority sitting inactive.
For new-authority carriers, this is the piece that trips people up most. You will usually need primary auto liability first, then cargo because nearly every broker and shipper asks for it, and then physical damage if you want your truck itself protected. We walk through that order with you so nothing gets filed late and your first loads are not held up.
What cargo insurance actually covers
Motor truck cargo insurance pays for the freight you are hauling when it is damaged or lost by a covered cause, such as a collision, fire, overturn or theft. It protects the goods, not your truck and not other people on the road. Those belong to physical damage and liability coverage.
The fine print matters more than the headline limit. Many cargo policies carry exclusions that surprise drivers after a claim, so we point them out before you sign.
- Commodity exclusions for certain goods, such as electronics, alcohol or high-theft loads
- Unattended vehicle rules that limit theft coverage when the truck is parked
- Reefer breakdown coverage, which is often an add-on rather than standard
- Debris removal and loading or unloading coverage, which vary by policy
What moves the premium on a cargo policy
Cargo premiums depend less on the truck and more on what is behind it. The type of freight is the biggest factor, since some commodities are stolen or damaged far more often than others. The limit you need, usually set by your brokers or lease, and the deductible you choose also shape the number.
Your radius, the states you run through, your claims history and how long you have been driving all play a part too. A driver hauling dry van general freight across the Southeast will be looked at differently than one pulling refrigerated food or steel. When you call, tell us what you haul and where, and we can give you a clear picture of your options.
What to have handy before we talk
A few documents make the call shorter and the answer more accurate. If you are leased on, the lease agreement matters most, because it spells out which coverage the carrier provides and which pieces you are expected to buy yourself.
If you are starting or running your own authority, we will look at the whole picture so your filings, certificate of insurance and policy limits line up before brokers start asking for them. Do not worry if you are missing something; we can start the call with what you have and talk through the rest together on the phone.
- Your DOT number and MC authority number, if you have them
- Your lease agreement, if you are leased to a motor carrier
- The cargo limits your brokers or shippers have asked for
- A rundown of what you haul, your usual lanes and your driving history
- Any current policy declarations page you already carry
More questions about cargo coverage
Do brokers accept a cargo-only certificate of insurance?
If you are leased to a carrier, brokers generally deal with that carrier, not you. If you run your own authority, brokers will want to see liability and cargo on your certificate of insurance, so cargo alone usually won't get you loaded.
Do I need non-trucking liability along with cargo?
Many leased owner-operators do. The carrier's liability usually covers you only under dispatch, so non-trucking liability, sometimes called bobtail coverage, protects you when you drive for personal reasons. Your lease often spells out whether it is required.
Can I add cargo coverage to a policy I already have?
Often, yes. We can look at your current coverage and tell you if adding cargo or setting up a separate policy makes more sense for your operation.
Not sure if cargo alone covers you?
Tell us if you are leased on or running your own authority, plus what you haul and where. We will look over your lease or current policy, explain what you actually need, and put together cargo or full trucking coverage options for you.